News / National
Delta, Zimra tax dispute heads to court
5 mins ago |
4 Views
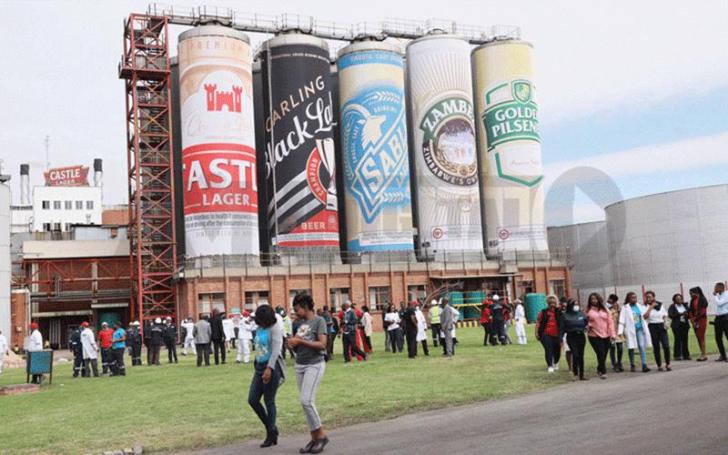
Zimbabwe's largest beverages manufacturer, Delta Corporation, is locked in a US$97 million tax dispute with the Zimbabwe Revenue Authority (ZIMRA), with the matter now before the Fiscal Court as the company challenges the calculation and treatment of its tax obligations.
The dispute involves value-added tax (VAT) and income tax assessments covering the period between 2019 and 2022, including an earlier US$74 million tax claim that has since grown through additional assessments.
At the centre of the disagreement is the treatment of payments made in Zimbabwe's local currency during periods of hyperinflation and exchange-rate instability.
Delta argues that ZIMRA failed to properly recognise or adjust for tax payments made in local currency when calculating the company's outstanding obligations.
The beverages manufacturer maintains that the payments were made using legally recognised currency at the time and should be appropriately credited against the assessed liabilities.
Presenting the group's financial results for the six months ended September 30, 2026, Delta chairman Todd Moyo confirmed that the dispute remained unresolved despite earlier legal proceedings concerning the validity of some assessments.
Moyo said that although the validity of the assessments relating to the 2019 to 2021 periods had been confirmed, significant disagreements remained over how the amounts were calculated.
These include the methodology used by ZIMRA, the apportionment of tax liabilities, the quantification of amounts allegedly owed and the currency in which the obligations should be expressed.
The outstanding issues are now before the Special Court for Income Tax Appeals, commonly referred to as the Fiscal Court.
He added that routine audits and reviews of other tax categories could continue as part of ZIMRA's normal operations.
Despite challenging the assessments, Delta has continued making payments towards the disputed amounts in accordance with Zimbabwe's tax collection framework.
Moyo revealed that the company had paid a cumulative US$22.8 million towards the disputed assessments as of September 30, 2026.
The payments were made under the country's "pay now, argue later" tax principle, which generally requires taxpayers to settle assessed obligations even while challenging them through the prescribed legal processes, subject to applicable relief.
Delta has also entered into payment arrangements with the revenue authority while pursuing its legal challenges.
Moyo expressed hope that any adjustments to the existing payment plans would take account of the company's position and the broader national interest.
He maintained that the principal tax amounts had already been paid in legal tender at the relevant times, based on what the company considered a reasonable interpretation of the applicable legislation.
The group has also proposed using its holdings of United States dollar-denominated Treasury bills to settle any portion of the disputed tax liability that may ultimately be confirmed as payable.
According to Moyo, Delta hopes the Government will consider accepting the Treasury instruments as an offset against any final liability arising from the legal proceedings.
The company has sought to distinguish the ongoing dispute from its broader record of tax compliance, maintaining that it continues to meet its obligations across various tax categories.
Moyo said Delta paid more than US$193 million in taxes in Zimbabwe during the six months ended September 30, 2026.
The figure represented a 31 percent increase compared with the corresponding period in the previous financial year.
The substantial payments, he argued, demonstrated the company's continued contribution to Government revenue despite its disagreement with ZIMRA over the historical assessments.
Delta also raised concerns about ambiguities within Zimbabwe's tax legislation, warning that differing interpretations of the law could result in further disputes between businesses and the revenue authority.
The dispute highlights the complexities businesses have faced in accounting for tax obligations during Zimbabwe's repeated currency changes and periods of significant exchange-rate volatility.
Questions surrounding the conversion of local-currency payments into United States dollar liabilities have become particularly contentious where tax assessments cover periods characterised by rapid inflation and changing monetary regulations.
For Delta, the outcome of the Fiscal Court proceedings will be significant in determining the extent of its outstanding obligations and whether previous payments should reduce the amounts claimed by ZIMRA.
The case could also provide guidance on how historical tax payments made in local currency should be treated under Zimbabwe's tax framework, although its wider implications will depend on the court's findings.
With approximately US$97 million in cumulative assessments under dispute, the proceedings represent a substantial financial matter for the beverages manufacturer.
For now, Delta maintains that it has complied with its tax obligations and will continue pursuing the available legal remedies to challenge the disputed calculations while honouring its existing payment arrangements.
The Fiscal Court is expected to determine the outstanding issues relating to the assessments, including their calculation, apportionment and currency treatment.
The dispute involves value-added tax (VAT) and income tax assessments covering the period between 2019 and 2022, including an earlier US$74 million tax claim that has since grown through additional assessments.
At the centre of the disagreement is the treatment of payments made in Zimbabwe's local currency during periods of hyperinflation and exchange-rate instability.
Delta argues that ZIMRA failed to properly recognise or adjust for tax payments made in local currency when calculating the company's outstanding obligations.
The beverages manufacturer maintains that the payments were made using legally recognised currency at the time and should be appropriately credited against the assessed liabilities.
Presenting the group's financial results for the six months ended September 30, 2026, Delta chairman Todd Moyo confirmed that the dispute remained unresolved despite earlier legal proceedings concerning the validity of some assessments.
Moyo said that although the validity of the assessments relating to the 2019 to 2021 periods had been confirmed, significant disagreements remained over how the amounts were calculated.
These include the methodology used by ZIMRA, the apportionment of tax liabilities, the quantification of amounts allegedly owed and the currency in which the obligations should be expressed.
The outstanding issues are now before the Special Court for Income Tax Appeals, commonly referred to as the Fiscal Court.
He added that routine audits and reviews of other tax categories could continue as part of ZIMRA's normal operations.
Despite challenging the assessments, Delta has continued making payments towards the disputed amounts in accordance with Zimbabwe's tax collection framework.
Moyo revealed that the company had paid a cumulative US$22.8 million towards the disputed assessments as of September 30, 2026.
The payments were made under the country's "pay now, argue later" tax principle, which generally requires taxpayers to settle assessed obligations even while challenging them through the prescribed legal processes, subject to applicable relief.
Delta has also entered into payment arrangements with the revenue authority while pursuing its legal challenges.
Moyo expressed hope that any adjustments to the existing payment plans would take account of the company's position and the broader national interest.
The group has also proposed using its holdings of United States dollar-denominated Treasury bills to settle any portion of the disputed tax liability that may ultimately be confirmed as payable.
According to Moyo, Delta hopes the Government will consider accepting the Treasury instruments as an offset against any final liability arising from the legal proceedings.
The company has sought to distinguish the ongoing dispute from its broader record of tax compliance, maintaining that it continues to meet its obligations across various tax categories.
Moyo said Delta paid more than US$193 million in taxes in Zimbabwe during the six months ended September 30, 2026.
The figure represented a 31 percent increase compared with the corresponding period in the previous financial year.
The substantial payments, he argued, demonstrated the company's continued contribution to Government revenue despite its disagreement with ZIMRA over the historical assessments.
Delta also raised concerns about ambiguities within Zimbabwe's tax legislation, warning that differing interpretations of the law could result in further disputes between businesses and the revenue authority.
The dispute highlights the complexities businesses have faced in accounting for tax obligations during Zimbabwe's repeated currency changes and periods of significant exchange-rate volatility.
Questions surrounding the conversion of local-currency payments into United States dollar liabilities have become particularly contentious where tax assessments cover periods characterised by rapid inflation and changing monetary regulations.
For Delta, the outcome of the Fiscal Court proceedings will be significant in determining the extent of its outstanding obligations and whether previous payments should reduce the amounts claimed by ZIMRA.
The case could also provide guidance on how historical tax payments made in local currency should be treated under Zimbabwe's tax framework, although its wider implications will depend on the court's findings.
With approximately US$97 million in cumulative assessments under dispute, the proceedings represent a substantial financial matter for the beverages manufacturer.
For now, Delta maintains that it has complied with its tax obligations and will continue pursuing the available legal remedies to challenge the disputed calculations while honouring its existing payment arrangements.
The Fiscal Court is expected to determine the outstanding issues relating to the assessments, including their calculation, apportionment and currency treatment.
Source - online
Join the discussion
Loading comments…